

A Dubai property payment plan tells you when money must leave your account. It does not, by itself, tell you whether the property is affordable, competitively priced, or suitable for your investment horizon. A small booking payment can sit alongside a large completion balance. A long schedule can be attached to a higher purchase price. Two apartments advertised with the same percentages can require very different amounts of cash in the next twelve months.
The useful comparison is therefore a dated cash schedule for a specific unit, including purchase costs, an operating reserve, and realistic funding assumptions. This guide explains how to build that comparison, identify the questions that matter before reservation, and prepare a shortlist your advisor can actually act on. All numerical examples are hypothetical teaching examples, not available offers or forecasts.
Illustrative property-planning scene from the Property Gulf media library; not a photograph of a unit offered for sale.
Start with the unit price, not the booking percentage
Imagine two apartments offered at AED 1,600,000 and AED 1,900,000. A ten percent booking payment would be AED 160,000 for the first and AED 190,000 for the second. The percentage looks identical, but the buyer needs an additional AED 30,000 immediately for the more expensive unit. The difference grows as later instalments fall due. Comparing the labels alone hides the actual commitment.
Ask for the dated quotation for the exact apartment, including the unit number, floor, layout, saleable area, furnishing specification, and parking allocation. Then request the payment schedule attached to that quotation. A project brochure may describe a typical plan without confirming that it applies to your chosen unit, release, or reservation date. The comparison should use written unit-specific terms rather than a screenshot forwarded without context.
Translate every percentage into a payment amount
A hypothetical 60/40 plan usually describes a split between payments before completion and a remaining portion at completion, but the shorthand is incomplete. You still need to know whether the booking amount is included in the sixty percent, how the construction instalments are distributed, and what event makes the last forty percent due. Never add the booking percentage twice or assume that equal instalments are implied.
For a hypothetical AED 1,800,000 purchase, sixty percent is AED 1,080,000 and forty percent is AED 720,000. If the booking payment is part of the first portion, it belongs inside the AED 1,080,000 total. Build a simple ledger with four columns: payment event, contractual date or trigger, percentage, and amount. The purchase-price payments should add to exactly one hundred percent, while other charges remain separately identified.
Separate calendar dates from construction milestones
Some instalments may fall due on calendar dates; others may depend on construction milestones or contractual notices. These are different funding problems. A salary-funded buyer can plan around a fixed date, while a milestone payment may arrive sooner or later than expected. Read the wording that determines the obligation, and ask who confirms a milestone and how notice is delivered.
Create two schedules if timing is uncertain. The first follows the developer's current expected timetable. The second groups plausible closely spaced payments into a more demanding cash period. This is not a prediction that the developer will accelerate collection. It is a practical check of whether your finances can absorb the timing flexibility already present in the documents. Keep the contractual obligation distinct from the marketing completion estimate.
Illustrative buyer-comparison scene from the Property Gulf media library.
Include acquisition costs outside the advertised plan
Your payment-plan spreadsheet is incomplete if it contains only the property price. Ask your advisor for a written estimate of transaction charges, registration-related costs, any brokerage fee, banking expenses, valuation costs if financing is involved, and applicable administrative charges. Mark each item as confirmed, estimated, or still awaiting clarification. Costs can depend on the transaction structure and the services required.
For the applicable transaction route, consult the Dubai Land Department sale-registration service and confirm the specific charges before committing. Do not assume that an advertised incentive removes every acquisition expense. If a developer offers to cover a charge, obtain written confirmation of the exact item, amount, conditions, and whether it changes the price or other terms.
Test the completion balance before paying the deposit
The most important number may be the amount due near handover. Buyers sometimes focus on manageable construction instalments while treating the completion payment as a future problem. That can work only if the future funding source is credible. A hoped-for resale, an unapproved mortgage, or anticipated rental income should not silently become the foundation of an otherwise affordable-looking purchase.
For the AED 720,000 hypothetical completion balance above, record how much will come from existing savings, expected accumulated savings, a confirmed asset sale, or financing subject to approval. Give each source a timing assumption and confidence level. If a substantial gap remains, choose a smaller commitment or obtain suitable advice before reserving. The useful result is a fundable purchase, not merely an attractive instalment headline.
Understand what post-handover actually changes
A post-handover schedule spreads some payments beyond the delivery event. It changes timing; it does not automatically make the apartment cheaper or eliminate the obligation to pay. Ask when the post-handover period starts, whether payments are monthly or quarterly, and how possession, registration, financing, and resale interact with the unpaid balance under the actual contract.
Do not assume rent will cover every instalment. A new property may need inspection, corrections, furnishing, marketing, and tenant onboarding before income begins. Even after occupancy, rent and instalments may arrive on different dates. Prepare a separate reserve for a period without rent and check whether the household or business can continue making payments if leasing takes longer than planned.
Compare total economics, not just payment convenience
If one unit has a longer plan and another has a lower cash price, compare their complete terms. The units may differ in view, floor, size, finish, or delivery risk, so avoid calling the entire price gap a financing cost without adjusting for those differences. Start with genuinely comparable properties, and document what still makes the comparison imperfect.
A useful decision table includes the total quoted price, cash needed immediately, cash needed within twelve months, largest single future payment, expected completion timing, and remaining balance after completion. Add the property differences in a separate column. This makes it easier to explain why a convenient plan may still be the weaker purchase, or why paying slightly more could suit a buyer with predictable future income.
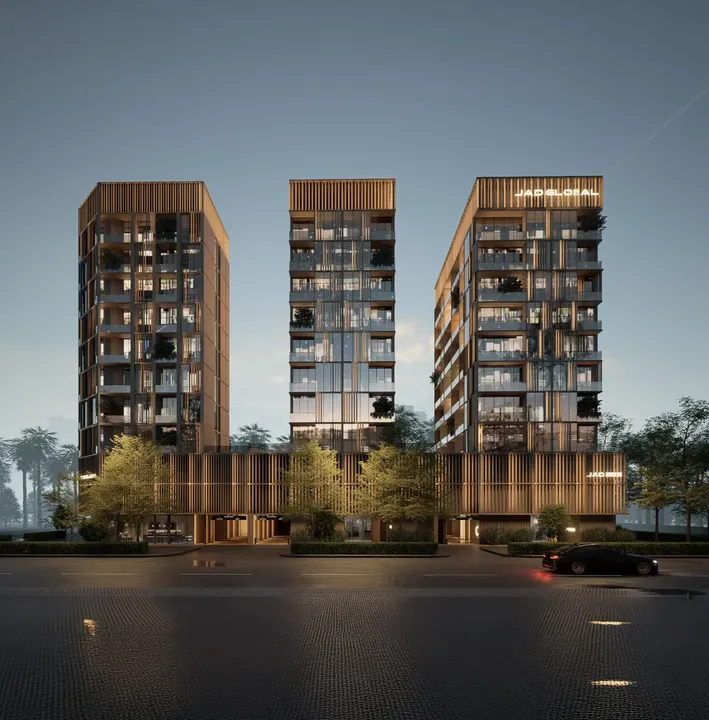
JAD 288 architectural visualization from the existing Property Gulf library. Shown as an example of project marketing imagery, not proof of delivered condition or availability.
Account for the currency in which you earn
An overseas buyer may earn and hold savings in a currency different from the payment currency. The relevant risk is the amount of home-currency cash needed on each due date, including transfer costs. Record the current conversion assumption and ask your bank or regulated currency provider how transfers, settlement times, and documentation will work. Do not assume a quoted exchange rate will remain available.
Run a hypothetical adverse-currency scenario without pretending to forecast exchange rates. For example, increase the home-currency cost of each remaining instalment by a chosen stress percentage and inspect the largest monthly or quarterly burden. The percentage is a planning assumption, not market guidance. Buyers with complicated cross-border finances should obtain advice appropriate to their circumstances before deciding how to fund payments.
Check the project and payment destination independently
Payment flexibility is not a substitute for verifying the project and seller. Dubai Land Department provides a project-registration service associated with off-plan escrow arrangements. Ask your advisor to help verify the relevant project records and confirm payment instructions through an independently authenticated channel. A familiar logo on a payment request is not enough evidence on its own.
Keep the reservation document, quotation, signed agreement, payment schedule, bank confirmation, receipts, and correspondence in one organized file. Match the unit identifier and purchaser details across the documents. If instructions change, pause to confirm them using a known contact rather than replying only to the message announcing the change. This is ordinary transaction hygiene and should happen before a deadline creates pressure.
Ask about resale, assignment, and early settlement
Your intended exit may be earlier than the end of the plan. Ask what contractual conditions apply if you want to sell or assign the property before completion, and whether payment thresholds, consent, charges, or other restrictions apply. These details vary, so a generic statement about what buyers usually do is not a substitute for your documents.
Also ask how early settlement is handled. A buyer whose finances improve may want to pay sooner, while another may want to refinance after completion. Get clear answers about the process and any applicable conditions. Do not build your investment case around an assumed discount, guaranteed buyer, or automatic financing approval. Treat each as a separate matter requiring confirmation.
Build a reserve that survives an inconvenient month
An emergency reserve is separate from money already allocated to property instalments. If the same cash appears in both categories, the plan is overstating your capacity. List household obligations, business working capital, existing borrowing, and foreseeable major expenses before deciding what can safely be committed. This is particularly important for buyers whose income fluctuates or depends on a single business.
Stress-test the timing rather than only the annual total. A purchase can look manageable over a full year yet create a difficult quarter when a large instalment coincides with school fees, tax payments elsewhere, or another property completion. A calendar view often reveals this problem faster than a headline budget. Select a plan that remains workable during the weakest plausible funding period.
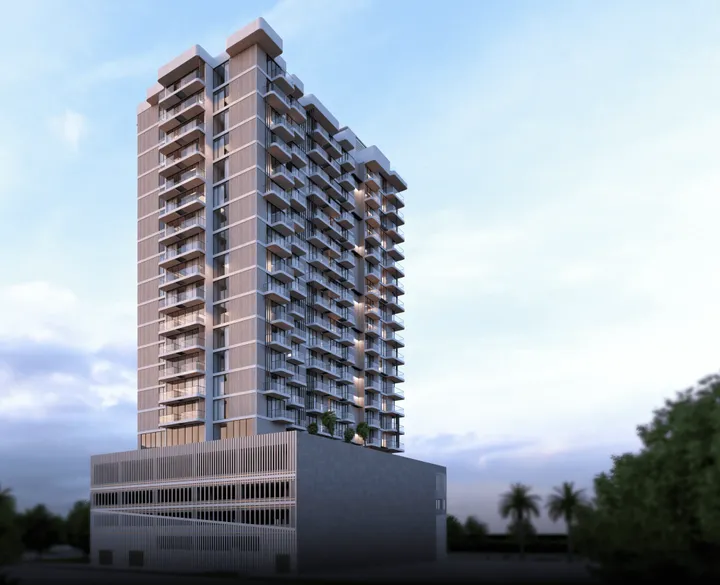
TETR1S Tower architectural visualization from the existing Property Gulf library. The actual unit, specification and current project status require separate verification.
A practical comparison meeting with your advisor
Bring your available initial cash, comfortable recurring contribution, preferred completion period, intended use, and funding currency. Ask for three suitable units rather than a long list of projects. Each option should show the same financial fields and its main trade-off. One might need more cash now; another might concentrate risk at completion; a third might offer a better location but less flexibility.
Request a written shortlist with a last-checked date, because prices and availability can change. Your advisor should distinguish confirmed inventory from an enquiry awaiting developer confirmation. If an option only works after changing your assumptions, make that change visible. The purpose of the meeting is to identify a property that fits your actual buying capacity and objectives, not to stretch your budget until a preferred advertisement appears affordable.
Keep a payment calendar after reservation
Once you commit, turn the agreed schedule into a calendar with reminders that allow time for transfers and document checks. Keep the contractual due date separate from your own earlier preparation date. Record each payment reference and reconcile it against the developer's statement so a transfer is not merely assumed to have been allocated correctly.
If your income, financing, or personal circumstances change, review the remaining schedule promptly. Ask the relevant professional about your actual options before a deadline arrives. Do not assume that an informal request automatically changes a contractual obligation. A useful calendar links each future payment to the funds intended for it and makes emerging gaps visible while there is still time to seek advice.
Frequently asked questions
Is the lowest down payment the best option?
Not necessarily. It reduces one early payment but can shift a larger obligation into later stages or accompany a higher price. Compare the complete dated schedule, the unit itself, and the funding source for the largest instalment. A lower starting payment is useful only when the remaining commitment also fits your finances.
Can I assume I will obtain a mortgage at handover?
No. Financing depends on lender requirements, the property, your circumstances, and the assessment at the relevant time. Seek lender guidance early and keep any conditions visible in your plan. A payment obligation should not be described as funded merely because a mortgage might become available later.
Does a post-handover plan guarantee positive cash flow?
No. Rental timing, vacancy, service charges, management expenses, repairs, and the size of remaining instalments all affect cash flow. Model rent conservatively and keep a cash reserve. The schedule may improve flexibility, but it cannot establish an investment return by itself.
What should I request before reserving?
Ask for the unit-specific quotation, complete payment schedule, relevant contract terms, itemized acquisition costs, project verification, authenticated payment instructions, and clarification of resale and cancellation conditions. Where legal interpretation is needed, use a qualified professional. Keep unresolved questions in writing rather than accepting verbal reassurance as a completed check.
Turn the comparison into a realistic shortlist
A useful payment plan is one you can follow without relying on an optimistic sequence of events. Start with the property, convert percentages into cash, add costs, test completion funding, and preserve a reserve. Then compare only units that meet those financial constraints. This usually makes the shortlist smaller and the final decision clearer.
Read Property Gulf's off-plan due-diligence guide for the broader purchase checks, or request a payment-plan shortlist with your budget, available down payment, and preferred handover period. Ask for current written terms for every recommended unit before making a reservation.